Your roof can still keep the rain out and be worth far less to your insurance company than it costs to replace.
That surprises homeowners all the time.
A 20-year-old roof could need $20,000 worth of work after a covered storm, yet an actual cash value policy might value that roof at only a fraction of the replacement cost. In one example used by insurance regulators, that fraction falls all the way to 20 percent.
The important question is how your policy says the roof will be valued when you file a claim.
Where the 20 Percent Number Comes From
Let’s clear up the headline first.
There is no nationwide rule saying every 20-year-old roof is worth 20 percent. Insurers use different policies, endorsements, depreciation methods and roof-payment schedules.
The 20 percent example comes from the National Association of Insurance Commissioners.
Its post-disaster claims guide explains that if a covered loss destroys a 20-year-old roof with an assumed useful life of about 25 years, an actual cash value policy could value the roof at about 20 percent of its replacement cost before the applicable deductible because most of its value has already been depreciated.
For a homeowner, that distinction can be huge.
Say replacing the roof costs $20,000.
| Claim basis | Simplified value before deductible |
|---|---|
| Replacement cost | $20,000 |
| 20% actual cash value | $4,000 |
| Difference | $16,000 |
Still, it shows why I tell homeowners to find out how their roof is insured before there is a storm.
After a tree limb comes through the shingles is a terrible time to learn what ACV means.
Replacement Cost and Actual Cash Value Are Very Different Things
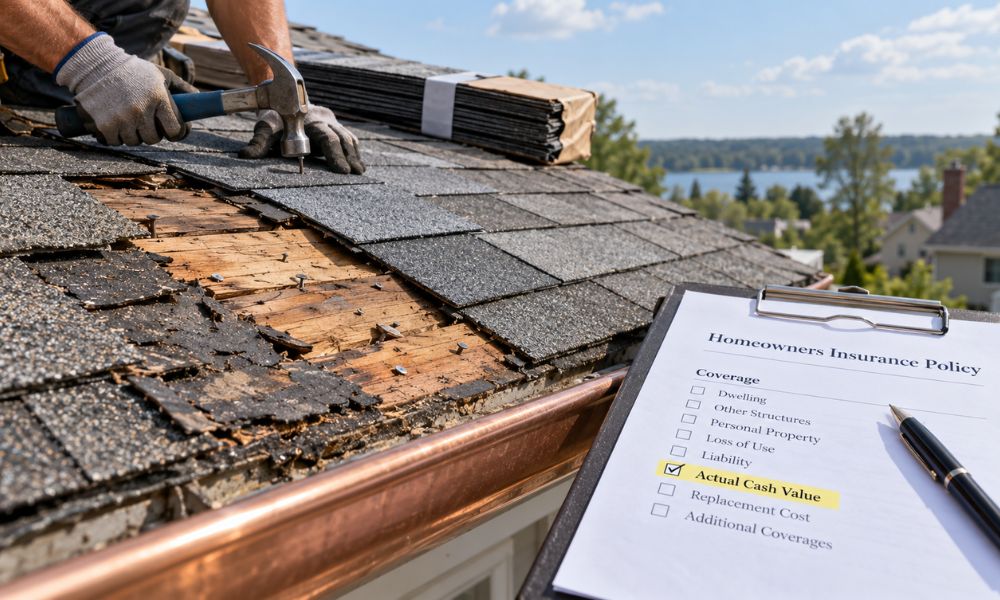
Most confusion starts with two terms: replacement cost value and actual cash value.
Replacement cost value, usually shortened to RCV, generally means the cost of repairing or replacing covered damaged property with materials of like kind and quality without subtracting depreciation.
Actual cash value, or ACV, accounts for depreciation.
The National Association of Insurance Commissioners explains ACV as repair or replacement cost adjusted for age and wear and tear. RCV coverage pays based on replacement cost without that depreciation deduction, subject to the limits and terms of the policy.
From a roofing standpoint, depreciation matters because roofs spend their entire lives outside.
Sun, heat, cold, wind, and normal aging all affect roofing materials over time. Asphalt shingles lose granules. Seal strips age. Flashing and exposed components weather. Materials that looked fresh at installation won’t have the same remaining life 15 or 20 years later.
An insurer looking at ACV is interested in the value remaining immediately before the covered loss.
A roofing contractor is looking at what it costs to put a functioning roof back on the house.
Those can be two very different numbers.
An Old Roof Can Produce a Tiny Claim Check
Texas gives homeowners a particularly useful example.
The Texas Department of Insurance shows a hypothetical house with a $10,000 roof replacement and a $4,000 deductible. In its ACV example, the roof values look like this:
- 5-year-old roof: $8,500 ACV
- 10-year-old roof: $7,000 ACV
- 20-year-old roof: $4,000 ACV
With the $4,000 deductible applied, the illustrated insurance payment on the 20-year-old roof becomes $0.
A homeowner can look at that situation and say, “But my roof was insured.”
It was.
The problem is what “insured” actually meant under the loss-settlement terms.
I run into a similar misunderstanding around roofing all the time. People hear that wind or hail is covered and assume a covered storm means the insurance company buys a new roof.
Coverage for the cause of damage and the method used to calculate payment are separate questions.
You need answers to both.
Roof Age Can Change Your Coverage
One reason I want homeowners checking policies every renewal is that roof coverage can change as the roof gets older.
You might remember buying replacement cost coverage years ago and assume nothing has changed.
Don’t assume.
The Texas Department of Insurance warns homeowners that roof age can affect how an insurer handles coverage and advises policyholders to review it when renewing. Its roof replacement guidance also explains why homeowners should keep insurers updated when a roof is replaced.
The South Carolina Department of Insurance gives homeowners similar advice when renewing home insurance, including checking how roof age and condition can affect coverage.
Age isn’t the only thing insurers look at.
Depending on the company and policy, roof material and condition can matter too.
From my side of the ladder, that makes sense. Two 15-year-old asphalt roofs can look completely different. One might have good ventilation, reasonable sun exposure, and plenty of usable life left. Another might be curling, losing granules, and showing years of neglected repairs.
The number on the calendar tells part of the story.
The roof itself tells the rest.
Some Policies Use a Roof Payment Schedule
ACV isn’t the only arrangement homeowners should watch for.
Some insurance products use a roof surface payment schedule. Instead of calculating the claim in the same way as ordinary replacement cost coverage, the insurer pays a predetermined percentage based on factors such as roof age and material.
Missouri’s Department of Commerce and Insurance maintains a useful roof coverage comparison showing how different insurers operating in the state handle roof losses. The examples include replacement cost coverage, ACV arrangements and roof endorsements that pay percentages according to age or roof type.
Policies vary enormously, so I wouldn’t take one company’s schedule in Missouri and assume yours works the same way in another state.
I would use it as proof that the words on the declarations page deserve more attention than most people give them.
Five Things I Would Ask My Insurer
- Is my roof covered at RCV or ACV?
- Is there a separate roof payment schedule?
- Does the settlement method change at a certain roof age?
- What deductible applies to wind or hail damage?
- Are there roof-specific endorsements or exclusions?
Get the answers in writing or locate the exact provisions in the policy.
“I’m pretty sure my agent said…” isn’t where I want to be after a hailstorm.
Your Deductible Can Hurt More Than the Depreciation
| Dwelling coverage | 1% deductible | 2% deductible | 5% deductible |
|---|---|---|---|
| $200,000 | $2,000 | $4,000 | $10,000 |
| $300,000 | $3,000 | $6,000 | $15,000 |
| $400,000 | $4,000 | $8,000 | $20,000 |
| $500,000 | $5,000 | $10,000 | $25,000 |
Don’t ignore the deductible.
A percentage deductible can be much larger than people expect because the percentage can be tied to the home’s insured value rather than the repair bill.
Imagine a house carrying $400,000 in dwelling coverage with a 2% deductible applicable to a particular loss.
That is an $8,000 deductible.
Now imagine an older roof with a heavily depreciated ACV.
The depreciation reduces the covered value first. The deductible then determines how much of the remaining covered loss is still yours to absorb, depending on the terms of the policy.
That is how you can have real storm damage and still receive far less money than you expected.
Whenever somebody tells me, “Insurance will take care of the roof,” my next question is usually:
Have you actually looked at the deductible?
A lot of people haven’t.
A Worn-Out Roof Isn’t the Same as a Storm-Damaged Roof
Here is another distinction homeowners need to understand.
Insurance isn’t a roof maintenance program.
Ordinary wear, deterioration and an old roof reaching the end of its service life are different from sudden damage caused by a covered event.
That distinction matters because a storm can expose every weakness in an old roof.
Maybe the shingles were already brittle. Maybe flashing had been patched three times. Maybe granule loss had been progressing for years. Then one hard windstorm comes through and suddenly shingles are missing.
Now everybody has to separate existing deterioration from new storm damage.
That is a much easier conversation when the roof and gutters were maintained and documented beforehand.
Take Pictures Before You Need Them
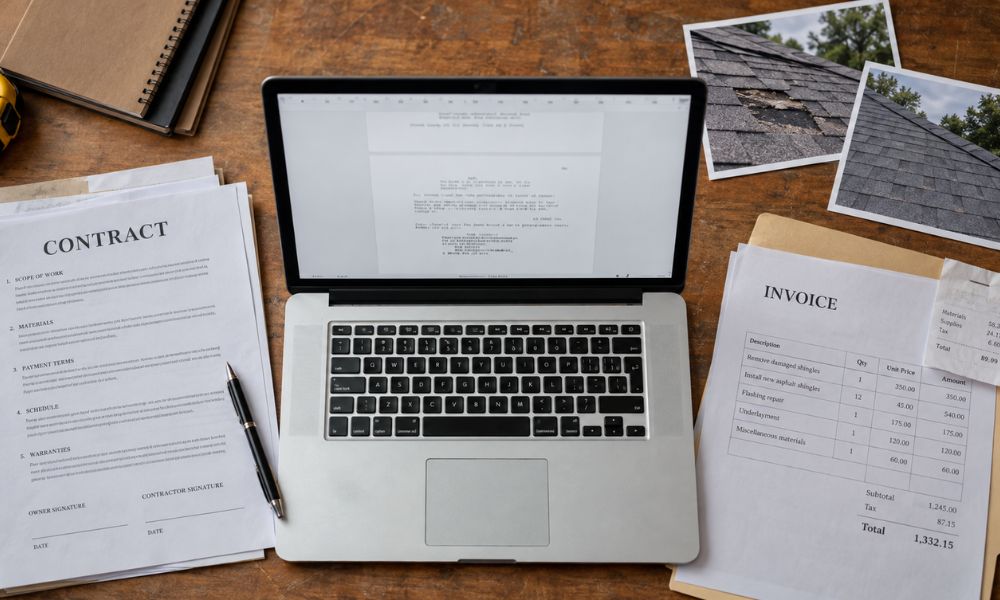
I am a big believer in boring documentation.
After a roof replacement, keep the invoice.
Keep the contract.
Save the material information.
Write down the installation date.
Take clear photographs.
If repairs are completed later, keep those invoices too.
When I inspect a house where the homeowner can tell me exactly when the roof was installed and show me records of major repairs, I already have better information than I get at plenty of properties.
It can matter for insurance as well.
Insurance departments advise homeowners to make sure details such as the age and condition of the property are correct when reviewing coverage. An incorrect roof age isn’t something I would leave sitting in an insurance file for years.
If you replaced a 22-year-old roof last summer and the insurer still thinks it is 22 years old, fix that record.
Don’t Replace a Roof Just Because Insurance Dislikes Its Age
I want to make one contractor point very clear.
An insurance company’s view of roof age isn’t automatically the same as my view of whether a roof needs replacement today.
I’ve looked at older roofs that were still performing adequately.
I’ve also looked at younger roofs I wouldn’t trust through another hard storm.
Installation quality, material, ventilation, weather exposure, previous repairs and maintenance all matter.
If an insurer tells you that your roof is too old for a certain type of coverage, that is an insurance issue.
If a qualified roofer tells you the roof is failing, that is a construction issue.
Sometimes the two line up.
Sometimes they don’t.
I wouldn’t spend thousands replacing a functional roof based solely on a vague fear about insurance. I would first find out exactly what the insurer requires, what coverage changes if I keep the existing roof and what the roof’s physical condition actually is.
Read the Roof Section Before Storm Season
Most people don’t read their homeowners policy until something has already happened.
I understand why. Insurance documents aren’t exactly Saturday-night entertainment.
The roof deserves an exception.
Find out whether you have replacement cost or actual cash value. Check for roof-specific endorsements. Look at the deductible. Confirm the roof age on file. Ask whether coverage changes as the roof gets older.
Then keep that information with your roofing records.
A roof can be perfectly capable of keeping your house dry while carrying very little insurance value under an ACV calculation.
Finding that out isn’t the problem.
Finding it out with shingles scattered across the yard is.
I’m Mike Carter, a roofing and gutter contractor who has spent most of my working life on roofs, up ladders and around job sites. I’ve worked with everything from asphalt shingles and metal roofing to flat roofs, flashing, fascia, gutters and drainage systems.
On Gutter N Roof, I share what I’ve learned from the years of experience, so homeowners can understand what’s happening above their heads and know when something needs attention.